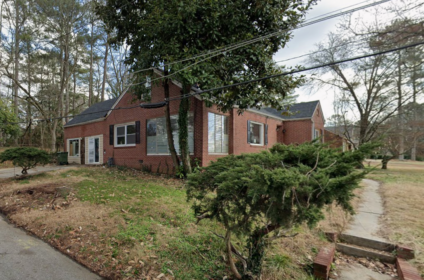
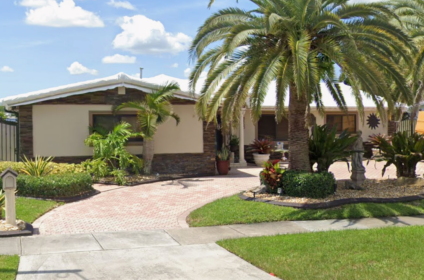
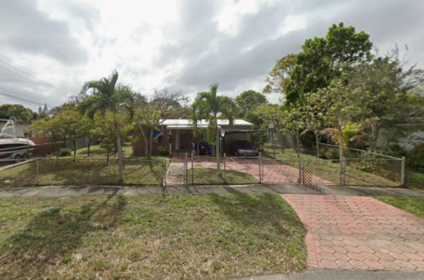
Here’s an in-depth analysis of the property at 621 NE 61st St, Oakland Park, FL 33334, focusing on its characteristics, the local market, and refinancing considerations:
Property Details:
- Address: 621 NE 61st St, Oakland Park, FL 33334
- Property Type: Single Family Home
- Bedrooms: 4 beds (though some public records initially show 2 beds/1 bath, detailed listings confirm 4 beds/2 baths, including a potential in-law suite with separate entrance)
- Bathrooms: 2 baths (2 full baths)
- Square Footage: 976 sqft (living area). This is a relatively compact home for 4 bedrooms.
- Lot Size: 7,238 sqft (approx. 0.16 acres)
- Estimated Refinance Payment: $3,200/mo (This is the payment provided in your input. This seems quite high for the stated value and current rates, especially for a 976 sqft home. It’s crucial to understand what this estimate includes, as it might already incorporate high taxes and insurance typical for this region.)
- Built in: 1958 (67 years old)
- Stated Value: $390,000 (This is the value provided in your input. This is generally consistent with current market estimates and recent sales for similar properties in the area.)
- Redfin Estimate: $456/sq ft (for 7,238 sq ft lot, not living area).
- Realtor.com RealEstimate℠: $394,100 for this specific home.
- Nearby Sold Comps (within 61st St area):
- 730 NE 61st St, Fort Lauderdale (same zip): Sold for $349,500 (recent).
- 540 NE 61st St, Fort Lauderdale (same zip): Sold for $399,900 (recent).
- 571 NE 61st St, Oakland Park (same zip): Listed for $379,900.
- 841 NE 61st St, Oakland Park (same zip): Listed for $389,900.
- 561 NE 61st St, Oakland Park (same zip): Listed for $399,900.
- 510 NE 61st St, Oakland Park (same zip): Listed for $409,900.
- Last Sale Price: The property last sold for $370,000 on August 18, 2021. This indicates some appreciation since the last sale, but not a drastic increase given your $390,000 value. The previous sale was for $102,000 in June 2001.
Financial Aspects & Fees:
- HOA Fees: None mentioned in records, typical for a single-family home not in a master-planned community.
- Property Taxes: This is a critical factor.
- 2024: $10,284 (on an assessed value of $461,530). This represents a massive +358.7% increase from 2023.
- 2023: $2,242
- 2022: $2,091
- The sharp increase in property taxes is a major component of the monthly housing cost and must be accurately accounted for in any refinance calculation.
- Homeowner’s Insurance: Florida has some of the highest and most volatile homeowner’s insurance rates in the nation, particularly in coastal areas prone to hurricanes.
- Average for Fort Lauderdale (nearby): $4,540/year ($378/month).
- Average for Oakland Park: Around $1,991/year ($166/month) by one source, but other sources for similar properties indicate higher, more realistic costs, often over $250-$350/month, and even higher for older homes. For a home built in 1958, rates can be significantly higher (e.g., average premium of $5,211 for homes older than 25 years in Fort Lauderdale).
- Expect this to be a significant ongoing cost.
Additional Property Features and History:
- Year Renovated: 1966 (per some records).
- Recent Updates (from 2021 listing): Freshly painted inside/outside (2021), termite treated (2020), crown molding, recessed lights in kitchen/living room.
- Interior Features: Tile floors, ceiling fans, blinds/shades. Appliances: disposal, dryer, electric range, microwave, refrigerator, washer. Potential separate guest/in-law quarters with a separate entrance and screened-in side porch.
- Exterior Features: CBS Construction (Concrete Block Stucco), Comp Shingle Roof, Fenced yard, Extra Building/Shed, Barbecue area, Fruit Trees. Complete accordion hurricane shutters.
- Utilities: Municipal Sewer, Municipal Water, Cable Available, Central Cooling (Electric), Central Heat (Electric).
- Location: Good location close to shopping, gym, theaters, dining, and major roads.
- Environmental Risks: Moderate Fire Factor (increasing), Severe Heat Factor, Extreme Wind Factor (typical for South Florida).
Oakland Park, FL (33334 Zip Code) Real Estate Market Trends (as of July 2025):
- Market Condition: The 33334 zip code is currently transitioning and is largely considered a Buyer’s Housing Market. This means prices tend to be lower, and homes stay on the market longer. This is a significant shift from a Seller’s Market a year ago.
- Median Sold Price (33334): $500,000 in June 2025, up 2.1% from last year, but this is an overall median for all home types.
- Median Sold Price for 4-bedroom homes (33334): Decreased by -1.3% year-over-year in June 2025.
- Average Home Value (Oakland Park overall): $370,571 (Zillow), down 4.0% over the past year.
- Median Days on Market: Homes are taking a long time to sell, averaging 113 days in June 2025, up 51.8% compared to last year. This indicates a very slow market where buyers have strong negotiation power.
- Sales-to-List Price Ratio: In June 2025, 75% of homes sold below asking price, and 0% sold over asking. This confirms a buyer’s market where price reductions and negotiations are common.
- Inventory: Increased by 16.7% month-over-month in June 2025, adding to buyer advantage.
Current Mortgage Refinance Rates in Florida (as of Monday, July 21, 2025):
- 30-Year Fixed Refinance: Average APRs are approximately 6.95% – 7.109%.
- 15-Year Fixed Refinance: Average APRs are around 5.90% – 5.95%.
- 5-Year Adjustable-Rate Mortgage (ARM): Average APRs are around 7.58% – 7.94%.
Note: These are average rates and are subject to change based on individual borrower qualifications (credit score, debt-to-income ratio), specific lenders, and daily market fluctuations. APR (Annual Percentage Rate) includes some fees beyond the interest rate.
General Requirements for Refinancing a Loan in Florida:
- Home Equity (Loan-to-Value Ratio – LTV): Most lenders require an LTV of 80% or less for conventional refinances (meaning you have at least 20% equity). A new appraisal will be required to determine the current market value and calculate your LTV.
- Credit Score: A minimum FICO score of 620 for conventional loans (higher scores get better rates).
- Debt-to-Income (DTI) Ratio: Lenders typically look for a DTI of 43% or lower, including the new mortgage payment, property taxes, and homeowner’s insurance.
- Property Occupancy: Must be your primary residence.
- Stable Income and Employment: Proof of consistent income and employment.
- Closing Costs: Expect to pay 2% to 6% of the new loan amount in closing costs (can range from $4,000 to $10,000+ for a $200k mortgage). These can sometimes be rolled into the new loan.
- Mortgage Insurance (PMI): If your LTV is above 80% on a conventional loan, you will likely be required to pay Private Mortgage Insurance (PMI).
Analysis for this specific property:
The most significant factor impacting refinancing for 621 NE 61st St is the dramatic increase in 2024 property taxes to over $10,000 annually. This translates to roughly $857 per month for taxes alone. Combined with high Florida homeowner’s insurance rates (potentially $300-$500+/month for an older home in this region), these fixed costs significantly impact the total monthly housing expense.
Your stated value of $390,000 aligns with current estimates and recent sales, and with a last sale of $370,000 in 2021, you likely have some equity built up. However, the current “Buyer’s Market” in 33334, with homes taking much longer to sell and often selling below asking, means an appraisal might come in conservative.
The estimated refinance payment of $3,200/mo seems high for a loan amount based on a $390,000 value at current rates, unless it heavily factors in the high taxes and insurance. For example, a $300,000 loan at 7% for 30 years is about $1,996 (P&I). Adding $857 (taxes) + $400 (insurance estimate) = $3,253/month. This suggests the $3,200/mo estimate is comprehensive and reflects the high cost of property taxes and insurance in this area.
Strong Recommendations for the Homeowner:
- Get a Precise Breakdown of the Estimated Payment: Immediately confirm what the $3,200/mo estimate includes. It is essential to know the exact breakdown of Principal & Interest, current 2024 Property Taxes ($10,284/year or approx. $857/month), and Homeowner’s Insurance. Do not proceed without this clarity.
- Obtain a Professional Appraisal: This is critical for all refinances, especially in a cooling market. It will provide the definitive current market value and allow for accurate LTV calculation.
- Confirm Current Loan Balance: Know your exact outstanding mortgage balance to determine your current equity.
- Shop for Personalized Refinance Offers: Contact multiple lenders. Be transparent about the property’s age and the high insurance/tax costs. Compare APRs, interest rates, all closing costs, and the full estimated monthly payment.
- Assess the “Why”: With the significantly increased property taxes, is the goal still to lower the monthly payment, or perhaps to consolidate other debt, or just to get a better rate? Understand that even a lower interest rate on the mortgage might not reduce the overall monthly housing expense if taxes and insurance remain so high.
- Review Insurance Options: Given the potentially very high homeowner’s insurance costs for an older home in Florida, explore all possible insurance providers and consider any mitigation efforts (e.g., wind mitigation inspection, roof updates) that could lower premiums.
Add Review