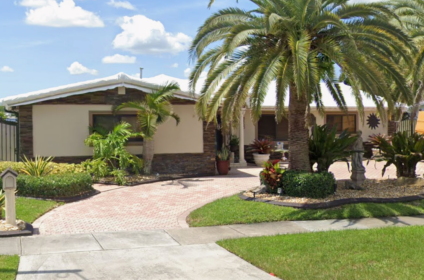
Here’s a detailed analysis of the property at 1474 13th St, West Palm Beach, FL 33401, focusing on its refinancing potential:
Property Snapshot:
- Address: 1474 13th St, West Palm Beach, FL 33401
- Property Type: Single Family Home
- Estimated Value: Your input: $343,400. Online estimates vary, from $340,500 (Zillow) to $381,885 (Redfin) and $383,597 (Xome). A professional appraisal is critical to confirm the precise current market value.
- Size: 1,232 sqft, 2 beds, 2 baths.
- Built: 1975 (Older home, which is a significant factor for homeowner’s insurance in Florida).
- Last Sold: June 28, 1990, for $58,000 (Redfin, Realtor.com). Earlier sales include $50,000 in Dec 1983 and $41,000 in April 1980. This indicates very substantial equity appreciation for the current owner.
- HOA Fees: Confirmed as No HOA Dues. This is a positive, as it eliminates an additional monthly cost.
Key Financials & Considerations for Refinancing:
- Significant Equity: Based on the 1990 purchase price and current estimated values, the homeowner has extremely significant equity, making this a very strong candidate for refinancing or a cash-out refinance.
- Property Taxes: Zillow indicates $859/year for 2024 (approx. $71.58/month). Other sources show $496/month in a Zillow monthly payment breakdown. This discrepancy needs to be verified. The actual annual tax amount reported by Zillow’s tax history for 2024 is $859. This is a relatively low fixed cost, likely due to Florida’s homestead exemption and “Save Our Homes” cap. Crucially verify the exact 2024 property tax bill for this address.
- Homeowner’s Insurance: This will be a very substantial monthly expense for a 1975-built home in West Palm Beach, Florida. While Redfin estimates $39/month and Zillow estimates $120/month, these figures are grossly unrealistic and dangerously understated for Florida’s current insurance market. For a home of this age and size in West Palm Beach, actual homeowner’s insurance premiums could realistically range from $500 to $1,000+ per month ($6,000 to $12,000+ annually). TGS Insurance states their customers in WPB typically pay around $3,833 annually for homes with an average value of $391,621. MoneyGeek reports the average for West Palm Beach at $1,093/month or $13,114 annually. Factors like the roof’s age and condition (Asphalt/Composition is listed), wind mitigation features (e.g., impact windows, hurricane shutters), and the specific insurer will heavily influence the actual premium. Do not proceed with refinancing without obtaining multiple, realistic, current insurance quotes tailored to this property.
- Refinance Rates: As of July 22, 2025, current Florida 30-year fixed refinance APRs are averaging around 6.75% to 7.18%.
Market Context (33401 Zip Code):
- Buyer’s Market: The 33401 zip code is currently “not very competitive.” Home prices were down 10.0% year-over-year in June 2025, with a median sale price of $493,000. Homes are taking longer to sell (95 days on average).
- Recent Trends: The median sale price per square foot in 33401 is $401, down 10.1% since last year. Homes are selling for about 7% below list price.
Recommendations:
- Obtain Multiple Realistic Homeowner’s Insurance Quotes: This is the single most important step for this property. Contact several independent insurance agents in Florida who specialize in older homes. Provide them with the home’s specifics (built 1975, 1,232 sqft, asphalt/composition roof, any recent roof replacement, hurricane-resistant features) to get accurate, current quotes. This will be the most significant variable in monthly housing costs.
- Verify All Monthly Costs: Get precise figures for the current 2024 property tax bill from Palm Beach County Property Appraiser’s office, as online estimates show some variation.
- Obtain a Professional Appraisal: This is essential to confirm the precise current market value, especially given the range in online estimates and the very old last sale date. An appraisal will also verify the square footage and any updates.
- Confirm Current Loan Balance: Understand your exact outstanding mortgage to accurately calculate your available equity.
- Shop Lenders Aggressively: Compare refinance rates, APRs, and closing costs from multiple lenders. Focus on the total loan cost, not just the interest rate.
- Define Refinancing Goals: Clearly identify what you hope to achieve with a refinance (e.g., lower interest rate, lower monthly payment, cash-out for home improvements or other investments). Consider if any renovations (like a new roof or impact windows) could significantly lower insurance premiums and be worth including in a cash-out refinance.
Add Review